مشاورهی وام مسکن، به زبان خودتانMortgage advice, explained clearly
خرید خانه، ریفایننس، تمدید یا وام بیزینس. گزینههای لندرهای مختلف را کنار هم میگذارم و همهی هزینهها را پیش از تصمیم برایتان توضیح میدهم.Buying, refinancing, renewing or a business loan. I compare options from multiple lenders and walk you through every cost before you decide, in Persian or English.
ریفایننس: قسط سبکتر، یا نقدینگی از خانهی خودتانRefinance for a lighter payment or cash from your home
بدهیهای پربهره را در وام مسکن جمع کنید یا برای بازسازی و سرمایهگذاری پول بگیرید. قبل از هر تصمیم، جریمهی فسخ وام فعلی و صرفهی واقعی را با هم حساب میکنیم.Roll high-interest debt into your mortgage or free up cash for renovations and investing. Before anything is decided, we work out your current prepayment penalty and the real savings together.
بدهیهای پربهره را در یک قسط، با نرخ وام مسکن جمع کنیدRoll high-interest debt into one payment at a mortgage rate
کارت اعتباری، لاین آف کردیت و لون ماشین را با اکوئیتی خانه تسویه کنید و بهجای چند قسط سنگین، یک قسط ماهانه بدهید. قبل از تصمیم، جریمهی فسخ وام فعلی و صرفهی واقعی را با هم حساب میکنیم.Pay off credit cards, lines of credit and car loans with your home equity, and make one monthly payment instead of several heavy ones. Before you decide, we work out your current prepayment penalty and the real savings together.
از ارزش خانهتان استفاده کنید، بدون شکستن وام فعلیUse your home's value without breaking your mortgage
با خط اعتباری (HELOC) یا وام دوم، به اکوئیتی خانه دسترسی پیدا میکنید و وام اصلی و نرخش دست نمیخورد. مقایسه میکنیم کدام راه برای شما ارزانتر تمام میشود.A home equity line of credit or a second mortgage gives you access to your equity while your current mortgage and its rate stay in place. We compare which route costs you less.
قبل از امضای نامهی تمدید بانک، گزینههای دیگر را هم ببینیدSee your other options before you sign the bank's renewal
پیشنهاد تمدید بانک فعلی همیشه بهترین نرخ نیست. چند ماه قبل از سررسید میتوانیم نرخ را رزرو کنیم و در صورت صرفه، وام را در زمان سررسید و معمولاً بدون جریمه به لندر دیگری منتقل کنیم.Your current bank's renewal offer isn't always its best rate. A few months before maturity we can hold a rate and, if it's worth it, move your mortgage at renewal, usually without a penalty.
بفهمید با شرایط امروزتان چقدر میتوانید خانه بخریدFind out how much home you can buy today
با توجه به درآمد، قسطها و پساندازتان، سقف خرید و قسط ماهانه را برایتان حساب میکنم و برای پیشتأیید (Pre-approval) آمادهتان میکنم. برای خریداران خانهی اول هم برنامههای کمکی وجود دارد.Based on your income, debts and savings, I'll work out your price range and monthly payment and get you ready for a pre-approval. First-time buyers have extra programs to lean on too.
خرید خانه یا ادامهی اجاره؛ کدام برای شما بهصرفهتر است؟Buy or keep renting: which makes more sense for you?
اجارهی فعلی، مدت ماندن و پساندازتان را کنار قسط ماهانه و هزینههای خرید میگذارم تا با عدد ببینید کدام راه برایتان بهتر است.I put your current rent, how long you plan to stay and your savings next to the monthly payment and buying costs, so you can see in numbers which way works better for you.
وام بیزینس، ساختمانی و خرید ملک تجاریBusiness, construction and commercial property loans
برای خرید ملک تجاری، ساختوساز یا سرمایهی بیزینس، پروندهتان را بررسی میکنم و گزینههای واقعبینانهی لندرهای مختلف را کنار هم میگذارم.Whether it's a commercial purchase, a construction project or capital for your business, I'll review your file and lay out realistic options from different lenders.
- مقایسهی لندرهای مختلف، نه فقط یک بانکOptions from multiple lenders, not just one bank
- همهی هزینهها و جریمهها، پیش از امضا روی میزEvery cost and penalty on the table before you sign
- جلسهی حضوری در مارکهام، یا تلفنی و آنلاینMeet in person in Markham, by phone or online
در چه کاری کمکتان میکنمWhat I can help with
موضوع خودتان را انتخاب کنید؛ سؤالهای ارزیابی و توضیحات این صفحه با همان هماهنگ میشود.Pick your situation. The assessment questions and this page adjust to it.
ریفایننس برای چه کاری؟What people refinance for
اکوئیتی یعنی فاصلهی ارزش امروز خانه با ماندهی وام. با ریفایننس میتوانید بخشی از آن را آزاد کنید.Equity is the gap between your home's value today and what you still owe. A refinance lets you free up part of it.
کارتهای اعتباری و لونهای پربهره را با نرخ وام مسکن، در یک قسط ماهانه جمع کنید.Fold credit cards and high-interest loans into one payment at a mortgage rate.
آشپزخانه، زیرزمین یا واحد اجارهای؛ پروژههایی که خانه را بهتر و باارزشتر میکنند.A kitchen, a basement or a rental suite: projects that make your home better and worth more.
اکوئیتی خانهی فعلی میتواند پیشپرداخت ملک بعدی شما باشد.The equity in your home can become the down payment on your next property.
با تغییر نرخ یا مدت بازپرداخت، فشار ماهانه را کم کنید؛ هزینهی کل را هم کنارش میبینیم.Change the rate or amortization to ease the monthly load, with the total cost shown alongside.
تجمیع بدهی چطور کمک میکندHow debt consolidation helps
بهرهی کارت اعتباری معمولاً چند برابر نرخ وام مسکن است. با اکوئیتی خانه میشود این بدهیها را یکجا تسویه کرد.Credit card interest is usually several times a mortgage rate. Your home equity can pay these debts off in one go.
کارتها، لاین آف کردیت و لون ماشین در یک قسط ماهانه با نرخ وام مسکن جمع میشوند.Cards, lines of credit and car loans become one monthly payment at a mortgage rate.
جمع قسطها معمولاً پایین میآید؛ هزینهی کل در طول مدت وام را هم کنارش نشانتان میدهم.Your total monthly payment usually drops, and I show you the total cost over the life of the loan alongside it.
ریفایننس، HELOC یا وام دوم؛ با در نظر گرفتن جریمهی وام فعلی، هر سه را کنار هم حساب میکنیم.Refinance, HELOC or a second mortgage: we cost out all three, including your current penalty.
اگر بدهیها روی امتیاز اعتباری اثر گذاشته، هنوز لندرهایی هستند که میشود با آنها کار کرد.If debt has pulled your score down, there are still lenders who can work with you.
HELOC یا وام دوم؛ کدام برای شما؟HELOC or second mortgage: which fits you?
هر دو به اکوئیتی خانه دسترسی میدهند و وام اصلی دست نمیخورد. تفاوتشان در هزینه و شرایط پذیرش است.Both give you access to your equity while your first mortgage stays put. They differ in cost and who qualifies.
اگر نرخ وام فعلیتان خوب است یا جریمهی فسخ سنگین است، معمولاً این راه بهصرفهتر است.If your current rate is good or the penalty to break it is steep, this is often the cheaper route.
هر وقت لازم داشتید برداشت میکنید و فقط برای همان مبلغ بهره میدهید.Draw what you need, when you need it, and pay interest only on what you use.
برای وقتی که درآمد یا اعتبار با معیار بانک جور نیست؛ نرخ بالاتر است و معمولاً کوتاهمدت استفاده میشود.For when income or credit doesn't fit bank rules. Rates are higher and it's usually a short-term tool.
هزینهی هر سه راه را کنار هم حساب میکنیم تا ارزانترین را انتخاب کنید.We cost out all three routes side by side so you can pick the cheapest.
تمدید، فرصتی برای شرایط بهترRenewal is your chance at better terms
زمان سررسید تنها وقتی است که میتوانید معمولاً بدون جریمه لندر یا شرایط وام را عوض کنید.Maturity is the one time you can usually change lenders or terms without a penalty.
چند ماه قبل از سررسید میشود نرخ را رزرو کرد؛ اگر نرخها پایین بیاید، پایینترین را میگیرید.A rate can be held a few months ahead. If rates drop in the meantime, you get the lower one.
نامهی تمدید را بفرستید؛ کنار گزینههای لندرهای دیگر میگذاریم و تفاوت را به دلار میبینید.Send me your renewal letter. We line it up against other lenders and you see the difference in dollars.
مدت، نوع نرخ (ثابت یا شناور) یا اضافه کردن مبلغ برای تجمیع بدهی؛ همه را میشود هنگام تمدید بازنگری کرد.Term, fixed or variable, or adding funds to consolidate debt can all be revisited at renewal.
اگر انتقال بهصرفه بود، کاغذبازی و هماهنگی با لندر جدید با من است.If switching makes sense, I handle the paperwork and coordination with the new lender.
پیش از گشتن دنبال خانهBefore you start viewing homes
اول بدانید چقدر میتوانید بخرید؛ هم انتخابها روشنتر میشود و هم در مذاکره دستتان پرتر است.Knowing your number first makes the search clearer and your offer stronger.
از درآمد، قسطها و پساندازتان حساب میکنم چه بازهی قیمتی و چه قسطی برایتان واقعبینانه است.From your income, debts and savings I work out a realistic price range and monthly payment.
با پیشتأیید، نرخ برای مدتی رزرو میشود و با اطمینان بیشتری پیشنهاد خرید میدهید.A pre-approval holds a rate for a period and lets you make offers with more confidence.
حساب FHSA، برداشت از RRSP و بازپرداخت مالیات انتقال (Land Transfer Tax)؛ میگویم کدام به کار شما میآید.FHSA, the RRSP Home Buyers' Plan and land transfer tax rebates: I'll show you which apply to you.
برای این شرایط هم برنامه و لندر مناسب وجود دارد؛ سابقهی کوتاه همیشه مانع نیست.There are programs and lenders for these situations too. A short history isn't always a dealbreaker.
خرید یا اجاره را با عدد مقایسه کنیمLet's compare buying and renting in numbers
جواب برای هر کس فرق میکند؛ به اجارهی فعلی، مدت ماندن و پسانداز شما بستگی دارد.The answer is different for everyone. It depends on your rent, how long you'll stay and your savings.
اجارهی امروزتان را کنار قسط، مالیات ملک و هزینهی نگهداری خانهای در همان بازهی قیمت میگذاریم.We set today's rent next to the payment, property tax and upkeep on a home in your price range.
هزینههای خرید و فروش در چند سال اول سنگین است؛ هرچه بیشتر بمانید، خرید معمولاً بهصرفهتر میشود.Buying and selling costs weigh most in the first few years. The longer you stay, the more buying tends to pay off.
FHSA، برداشت از RRSP و بازپرداخت مالیات انتقال میتواند پیشپرداخت را سبکتر کند.The FHSA, the RRSP Home Buyers' Plan and land transfer tax rebates can lighten the down payment.
اگر عددها نشان بدهد اجاره فعلاً بهتر است، همین را میگویم و برنامهای برای آماده شدن میچینیم.If the numbers say renting is better for now, I'll tell you, and we'll map out a plan to get ready.
تأمین مالی برای کار و ساختوسازFinancing for business and building
این وامها از وام مسکن معمولی پیچیدهترند؛ آماده بودن مدارک از اول، زمان را خیلی کوتاه میکند.These loans are more involved than a regular mortgage. Having documents ready early saves a lot of time.
مغازه، دفتر، ساختمان چندواحدی یا ملک صنعتی.Retail, office, multi-unit or industrial property.
تأمین مالی مرحلهبهمرحله (Draw) برای ساخت یا بازسازی اساسی.Funds released in stages (draws) for a new build or major renovation.
سرمایهی کار یا توسعهی بیزینس، گاهی با پشتوانهی ملک.Working capital or expansion, sometimes secured by real estate.
صورتهای مالی بیزینس، اظهارنامههای مالیاتی و برای ساختوساز، نقشه و بودجهی پروژه.Business financials, tax returns and, for construction, plans and a project budget.
روند کارHow it works
ساده و شفاف، بدون فشار برای تصمیمگیری.Simple and transparent, with no pressure to decide.
حدود یک دقیقه؛ بدون استعلام اعتباری و بدون تعهد.About a minute, with no credit check and no obligation.
با شما تماس میگیرم، شرایطتان را دقیق بررسی میکنم و گزینههای لندرها را کنار هم میگذاریم.I call you, go through your situation and we compare options from different lenders.
همهی هزینهها، جریمهها و شرایط را توضیح میدهم تا با خیال راحت تصمیم بگیرید.I explain every cost, penalty and condition so you can decide with peace of mind.
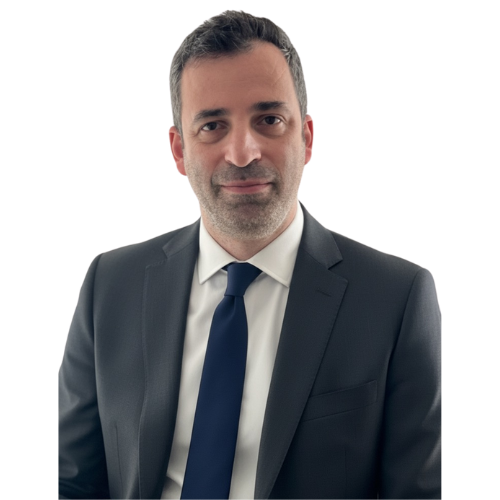
علیرضا عسگریانAlireza Asgarian
در 8Twelve Mortgage Corp به خانوادههای فارسیزبان کانادا کمک میکنم تا برای خرید خانه، ریفایننس، تمدید و وام از اکوئیتی، با آگاهی کامل و به زبان خودشان تصمیم بگیرند. هدفم این است که پیش از امضای هر قراردادی، دقیقاً بدانید چه چیزی را انتخاب میکنید.At 8Twelve Mortgage Corp, I help families across Canada make informed decisions about buying, refinancing, renewing and home equity, in Persian or English. My goal is simple: before you sign anything, you know exactly what you're choosing.
- دارای مجوز رسمی از FSRA، سازمان تنظیم مقررات خدمات مالی انتاریوLicensed by FSRA, the Financial Services Regulatory Authority of Ontario
- کارگزاری 8Twelve Mortgage Corp، دارای مجوز در ۱۳ استان و قلمرو کاناداBrokerage: 8Twelve Mortgage Corp, licensed in 13 provinces and territories
- 55 Renfrew Dr, #201, Markham, ON L3R 8H3
شفافیت، قبل از هر چیزTransparency first
چیزهایی که از همان گفتوگوی اول میتوانید رویش حساب کنید.What you can count on from the very first conversation.
استعلام فقط وقتی انجام میشود که تصمیم به ادامه بگیرید و اجازه بدهید.A credit check only happens if you decide to go ahead and give permission.
کارمزدها، جریمهی فسخ وام فعلی و هزینههای جانبی پیش از امضا توضیح داده میشوند.Fees, prepayment penalties and other costs are explained before you sign.
مشاوره رایگان است و هیچ اجباری برای ادامهی کار ندارید.The consultation is free and you're never obligated to go ahead.
فقط برای بررسی شرایط و تماس با خود شما استفاده میشود.It's used only to review your situation and to contact you.
سؤالهای رایجCommon questions
حداقل پیشپرداخت چقدر است؟What's the minimum down payment?
از ۵٪ شروع میشود و به قیمت خانه بستگی دارد. با پیشپرداخت کمتر از ۲۰٪، بیمهی وام مسکن هم لازم است. در جلسه دقیق برای قیمت مورد نظر شما حساب میکنیم.It starts at 5% and depends on the purchase price. Under 20% down, mortgage default insurance is required. We'll work out the exact figure for your price range.
پیشتأیید روی امتیاز اعتباریام اثر دارد؟Does a pre-approval affect my credit score?
برای پیشتأیید یک استعلام اعتباری لازم است که فقط با اجازهی شما انجام میشود. اثرش معمولاً جزئی و موقتی است. این ارزیابی اولیه هیچ استعلامی انجام نمیدهد.A pre-approval needs a credit check, done only with your permission. The effect is usually small and temporary. This first assessment involves no check at all.
ریفایننس برای من مناسب است؟Is refinancing right for me?
اگر بدهی پربهره دارید، برای بازسازی یا سرمایهگذاری پول لازم دارید یا قسط فعلی سنگین است، ممکن است مناسب باشد. جریمهی فسخ وام فعلی را هم حساب میکنیم و اگر HELOC یا وام دوم ارزانتر بود، همان را پیشنهاد میکنم.If you carry high-interest debt, need funds for renovations or investing, or your payment feels heavy, it may be. We factor in your current penalty, and if a HELOC or second mortgage is cheaper, that's what I'll suggest.
بانکم نامهی تمدید فرستاده؛ باید امضا کنم؟My bank sent a renewal letter. Should I just sign?
عجله نکنید. نامه را برایم بفرستید تا با گزینههای دیگر مقایسه کنیم. اگر پیشنهاد بانک خودتان بهتر بود، همان را امضا میکنید.Not yet. Send it over and we'll compare it with other options. If your bank's offer is the best one, you sign it.
بررسی وام بیزینس چقدر طول میکشد؟How long does a business loan take?
بستگی به نوع وام و آماده بودن مدارک دارد. بعد از گفتوگوی اول، فهرست دقیق مدارک و زمانبندی واقعبینانه را میگویم.It depends on the loan type and how ready your documents are. After our first call I'll give you an exact document list and a realistic timeline.
این ارزیابی روی امتیاز اعتباری من تأثیر دارد؟Will this assessment affect my credit score?
خیر. پاسخ دادن به این سؤالها هیچ استعلام اعتباری انجام نمیدهد.No. Answering these questions doesn't trigger any credit check.
مشاوره هزینه دارد؟Is there a fee for the consultation?
جلسهی مشاوره رایگان است. در بیشتر وامهای مسکن معمولی، کارمزد مشاور را لندر پرداخت میکند. اگر در پروندهای هزینهای وجود داشته باشد، پیش از هر اقدامی بهطور شفاف گفته میشود.The consultation is free. For most standard mortgages, the lender pays the advisor's fee. If a particular file involves a fee, you'll be told clearly before anything happens.
اگر خوداشتغال باشم یا اعتبارم ضعیف باشد چه؟What if I'm self-employed or have bruised credit?
برای این شرایط هم لندرها و برنامههای مختلفی وجود دارد. با بررسی پرونده، گزینههای واقعبینانه را معرفی میکنم.There are lenders and programs for these situations too. After reviewing your file, I'll present realistic options.
جلسه حضوری است یا آنلاین؟Do we meet in person or online?
هر دو. در دفتر مارکهام، تلفنی یا آنلاین؛ هر کدام برایتان راحتتر است.Either. At the Markham office, by phone or online, whichever suits you.
ببینید چه گزینههایی داریدSee what options you have
یک دقیقه وقت بگذارید؛ بقیهاش با من.Give it a minute. I'll take it from there.